If you’ve been looking at Toronto real estate, you’re probably holding off right now. The Bank of Canada raised its rate to 2.5% in October 2026, its first hike since 2023. The market was already slow, and more hikes could push prices down even further.
So why buy now, when it might be cheaper next year? That’s the question we answer in this post.
We break down what the latest inflation numbers really say, what the Bank is watching before its next decision on December 9, 2026, whether fixed or variable makes more sense right now, and what a good Toronto multiplex deal looks like today.
What October’s Inflation Numbers Really Say
Stats Canada says inflation was 3.1% in October 2026, the same as September and a bit lower than the 3.2% economists expected. But almost all of that came from gas. Gas prices were up about 31% from a year ago because of the war in the Middle East.
Take gas and energy out, and inflation was about 2%. The measures the Bank watches most closely, the ones that strip out big price swings like gas, were also right around 2%. That’s exactly the Bank’s target.
October 2026 Inflation
Source: Stats Canada, October 2026. The Bank of Canada targets 2%.
So why did the Bank raise rates in October if most prices are calm? It’s not worried about today. It’s worried about next year. High fuel prices raise the cost of making and shipping almost everything. And in the Bank’s own business survey, firms that saw bigger cost increases said they expect to pass more of them on to customers over the next year.
What the Bank of Canada Is Watching Before Its Next Move
Before its next move, the Bank is watching three things:
| Is Inflation Spreading Beyond Gas? If gas costs start pushing up rent, groceries and everything else, the Bank has more reason to hike. |
| Are Oil Prices Staying High? Oil is the main reason inflation jumped. If it comes down, so does the pressure to raise rates. |
| Is the Job Market Holding Up? The Bank’s job is inflation, not jobs. But jobs tell it where inflation is heading. If people lose work, they spend less, and that cools prices on its own. |

Right now, the job market is on the weak side. More people are out of work than a couple of years ago, and it hasn’t improved in months. The next jobs report comes out December 4, just days before the December 9 decision.
So what do the experts think? They’re split. Some big banks, like CIBC, expect the Bank to hold in December. Others, like RBC, still expect a hike. When economists can’t agree on the next few weeks, nobody really knows where rates will be a year from now. You can follow every call on our Canada interest rate forecast.
What markets are betting on is about three more hikes over the next year, 25 basis points each. That’s nothing like 2022. But if gas costs start pushing up rent, groceries and everything else, the Bank could hike more than markets expect. And if oil prices come down or more people lose their jobs, it could hike less, or stop altogether.
Is This 2022 All Over Again?
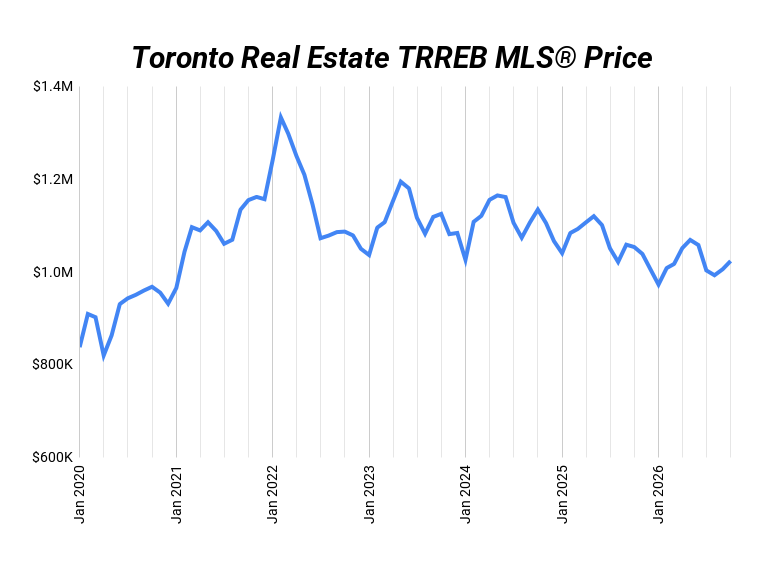
The last time the Bank started hiking, in 2022, it raised rates more than 400 basis points, and Toronto prices dropped hard. Today the average GTA home is still about 23% below that peak.
But back then, rates started near zero and buyers were paying way over asking. This time, markets expect only about 100 basis points of hikes, and prices have already come down. Toronto detached homes are selling for about 3% under asking on average.

Where Toronto Is Still Busy
Not every part of Toronto is slow. End-user homes in great neighbourhoods are still getting multiple offers on offer night. That’s East End starter homes, and move-up homes in prime spots like the Annex, Little Italy and Midtown. Buyers still want a deal, so they’re not going way over asking, but they’re still competing.
Where the Deals Are
Multiplexes are a different story. They’re a discretionary purchase, and fewer investors are buying right now. Sellers with an offer night often price low on purpose to bring more people in, and many of those offer nights flop. Sometimes the house still sells above asking, but most times, surprisingly, it sells pretty close to the list price.
The best deals are usually the ones that have been sitting with no offer night, especially after a price cut. That’s where you’re more likely to find a motivated seller. Not every seller will budge, but when one will, start lower and work your way up. You can track how the market is moving on our Toronto market updates page.
Fixed or Variable Right Now?
As of November 2026, the best variable rates are around 3.75% and the best fixed rates are around 4.6%. If markets are right and we get about three more hikes, variable ends up around 4.5%.
| Variable today | 3.75% |
| Variable after about 3 hikes | About 4.5% |
| Fixed today | 4.6% |
Best available conventional rates, November 2026. Confirm with your mortgage broker. For educational purposes only.
So even after those hikes, variable still comes out a bit cheaper, and you get months at a lower rate on the way up. But rates could go up more than markets expect. That’s what happened in the last round of hikes. If it happens again, there could be a stretch where variable costs you more than fixed.
How that hits you depends on your lender. Some lenders raise your payment right away. With others, your payment stays the same, but more of it goes to interest and less goes to paying down your mortgage. Here’s what that looks like on a $960,000 mortgage with a 30-year amortization, if variable goes from 3.75% to 4.5%:
| Adjustable Payment | Fixed Payment | |
|---|---|---|
| Payment at 3.75% | $4,430 | $4,430 |
| Payment at 4.5% | $4,840 | $4,430 |
| Goes to principal | $1,274 | $863 |
| Common with | Scotiabank | TD, RBC, BMO, CIBC |
First month after the rate change. For educational purposes only. Check your own lender’s terms.
With a fixed payment, you pay down your mortgage more slowly, so you owe more when you renew. And if rates climb a lot, your payment can stop covering the interest. That’s called the trigger rate, and when you hit it, the lender will raise your payment anyway. You can find yours with our trigger rate calculator.
Should You Wait for Prices to Drop?
In our opinion, you don’t have to. If you can get a discount from a seller today, you’ve already got what you were waiting for, and it may or may not happen across the market next year.
Just run your numbers at today’s fixed rate, even if you’re going variable. If the deal still cash flows well there, you’ve got room if rates keep going up. And know your rents. Rents have been moving around a lot, so use what units are actually renting for today.
Here’s what a lot of buyers don’t realize: in this market, sellers are accepting conditional offers. That means your offer gets accepted, but you still have time to do inspections, get contractor quotes, line up financing and check your numbers. If something doesn’t work, you can walk away. Once it’s accepted, the ball is in your court. In 2022, buyers had to skip all of that just to compete.
Two Deals We’re Seeing for Clients
Turnkey: a great deal, not a typical one. A house for about $1.1 million with a 3-bedroom upper, a 2-bedroom main floor and a 1-bedroom basement, bought with 20% down at 4.6% over 30 years.
| Rent: 3-bed, 2-bed and 1-bed basement | $3,500 + $2,800 + $1,800 |
| Total rent | $8,100 |
| Mortgage ($880,000) | -$4,488 |
| Taxes, insurance and upkeep | -$1,500 |
| Cash flow | $2,112 a month |
| Cash in (20% down plus closing) | $250,000 |
| Year 1 return (cash flow plus mortgage paydown) | About 15.8% |
For educational purposes only. Actual figures and returns may vary.
Project: renovate, then refinance. Buy a house for about $900,000, turn it into three 2-bedroom units, then refinance at 80% of the new value.
| Down payment, closing and $150,000 renovation | $350,000 |
| Cash flow before the refinance ($720,000 mortgage) | $2,728 a month |
| Value after the renovation | $1,200,000 |
| New mortgage at 80%, cash pulled back out | $960,000 / $240,000 |
| Cash left in the deal | $110,000 |
| Rent: upper, main and basement 2-beds | $3,000 + $3,000 + $2,100 |
| Mortgage, taxes, insurance and upkeep after the refinance | -$4,896 – $1,700 |
| Cash flow after the refinance | $1,504 a month |
| Year 1 return on cash left in | About 30.3% |
For educational purposes only. Actual figures and returns may vary.
| Turnkey | Project | |
|---|---|---|
| Cash left in | $250,000 | $110,000 |
| Cash flow | $2,112 a month | $1,504 a month |
| Mortgage paid down, year 1 | $14,055 | $15,333 |
| Year 1 return | 15.8% | 30.3% |
Cash flow plus mortgage paydown, divided by cash left in. Before any appreciation. For educational purposes only.
The turnkey is simpler, and you’re collecting rent as soon as you close. The project takes more work, but your money works a lot harder. Both returns are before any market appreciation, so if prices go up even a little over the next few years, they get better. You can see what Toronto multiplexes really cost and earn, or plug your own numbers into our investment calculator.
You Don’t Need the Bottom to Get a Good Deal
We’re not saying rates are done rising, or that prices have bottomed. Nobody knows that. We’re saying you don’t need either one. If a deal cash flows well at today’s rates and today’s rents, a December hike won’t change that, and a hold just makes it better.
The hard part is finding the sellers who will actually move on price, and knowing which deals still work with a cushion. That’s where an experienced team makes the difference.
Our brokerage specializes in Toronto multiplexes. We’ll help you find deals, crunch the numbers, and guide you through renovations and management. If you want full support in Toronto multiplex investing, our team can help you:- Find high-potential properties
- Crunch the numbers so you know exactly where you stand
- Coach you through renovations to maximize returns
- Lock in great tenants
- Provide full property management so your investment runs smoothly
What do Toronto multiplexes really cost and earn?
We pulled the numbers from the 50+ deals we worked on in the past year: build costs, rents by unit type, and how the refinances came out. Free, and no best case.
