Overnight Rate
2.50%
Prime Rate
4.70%
Last Updated
October 28, 2026
Next Decision
December 9, 2026
The Bank of Canada Rate Since 2022
HikesCutsPeak and now
5.00%
2.50%
2022
2023
2024
2025
2026
Each bar is a rate change. Hover over a bar to see the date and rate.
What This Means for Your Mortgage
| Best 5-Year Rates | This Summer | Now |
|---|---|---|
| Fixed | ~4.0% | 4.5–4.6% |
| Variable | ~3.5% | 3.75–3.85% |
For educational purposes only. Rates vary by lender and borrower.
| Fixed Certainty. Your payment is locked for the term. |
| Variable Lower rate today and smaller penalties to break, but it rises with each hike. If hikes continue into 2027, variable could get close to today’s fixed rate, though you’d enjoy lower rates for some months first. |
| Rate Holds Most lenders will hold a rate for 90 to 120 days, so lock one in if you’re shopping. |
See Your New Payment
Try the Mortgage CalculatorWhat the Bank of Canada Is Seeing Right Now
| Inflation 3.1% in September, but 2.2% without gas. Core inflation is 1.8% to 1.9%. About half of businesses plan to pass on higher energy and tariff costs. |
| Jobs and Growth The economy bounced back in the spring but is slowing. Canada lost 68,000 jobs in September, unemployment rose to 6.5%, and US tariffs are hurting exports and investment. |
| The Bank’s Stance It moved early to get ahead of inflation. If energy and tariff costs spread beyond gas, expect more hikes. If job losses deepen, expect a pause. |
Where Are Interest Rates Going in Canada?
Big five bank forecasts as of October 2026.
| Bank | Now | Dec 2026 | Mar 2027 | Jun 2027 | Dec 2027 |
|---|---|---|---|---|---|
 |
2.50% | 2.50% | 2.75% | 2.75% | 2.75% |
 |
2.50% | 2.50% | 2.75% | 2.75% | 2.75% |
 |
2.50% | 2.50% | 2.75% | 2.75% | 2.75% |
 |
2.50% | 2.50% | 2.50% | 2.75% | 3.25% |
 |
2.50% | 2.50% | 3.00% | 3.25% | 3.25% |
How Mortgage Rates Are Set
| Product | Estimate |
|---|---|
| 3-year fixed | 3-year bond yield + about 1% |
| Prime | Bank of Canada rate + 2.2% = 4.70% |
| Variable mortgage | Prime – 0.85% = about 3.85% |
| HELOC | Prime + 0% to 2% |
Estimates only. Fixed rates move ahead of the Bank with the bond market; variable rates move only when the Bank acts.
Bank of Canada Decisions
| Date | Rate | Change |
|---|---|---|
| 2026 | ||
| December 9, 2026 | TBC | TBC |
| October 28, 2026 | 2.50% | +0.25% |
| September 2, 2026 | 2.25% | — |
| July 15, 2026 | 2.25% | — |
| June 10, 2026 | 2.25% | — |
| April 29, 2026 | 2.25% | — |
| March 18, 2026 | 2.25% | — |
| January 28, 2026 | 2.25% | — |
| 2025 | ||
| December 10, 2025 | 2.25% | — |
| October 29, 2025 | 2.25% | –0.25% |
| September 17, 2025 | 2.50% | –0.25% |
| July 30, 2025 | 2.75% | — |
| June 4, 2025 | 2.75% | — |
| April 16, 2025 | 2.75% | — |
| March 12, 2025 | 2.75% | –0.25% |
| January 29, 2025 | 3.00% | –0.25% |
Rates by Year
| Year | Start | End |
|---|---|---|
| 2026 (so far) | 2.25% | 2.50% |
| 2025 | 3.25% | 2.25% |
| 2024 | 5.00% | 3.25% |
| 2023 | 4.25% | 5.00% |
| 2022 | 0.25% | 4.25% |
| 2021 | 0.25% | 0.25% |
| 2020 | 1.75% | 0.25% |
| 2019 | 1.75% | 1.75% |
| 2018 | 1.00% | 1.75% |
| 2017 | 0.50% | 1.00% |
| 2016 | 0.50% | 0.50% |
| 2015 | 1.00% | 0.50% |
Rates don’t move in a straight line.
Value-Add Deals: Better Returns, Lower Risk
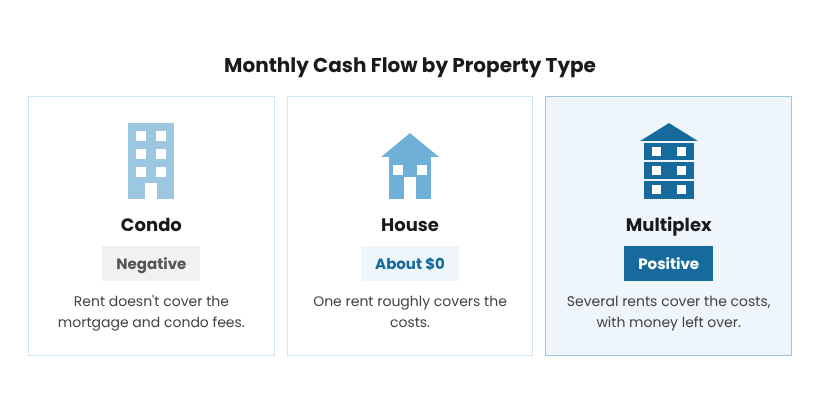
What Should Investors Focus On Right Now?
| Cash Flow From Day One The deal should pay for itself now, not someday. |
| Legal Multi-Units In stable, working neighbourhoods with steady rental demand. |
| Room to Add a Unit Properties with garden or laneway suite potential. |
| A Rate Buffer Run your numbers at 4.6% to 4.75%, and only buy where the cash flow still works. |
| Flexibility Choose financing that lets you refinance or sell if you need to. |
Stress-Test Your Next Deal
Try the Investment CalculatorWhat Rising Rates Mean for Real Estate Investors
- Find high-potential properties
- Crunch the numbers so you know exactly where you stand
- Coach you through renovations to maximize returns
- Lock in great tenants
- Provide full property management so your investment runs smoothly
What do Toronto multiplexes really cost and earn?
We pulled the numbers from the 50+ deals we worked on in the past year: build costs, rents by unit type, and how the refinances came out. Free, and no best case.
~$50KBasement suite
$2,6502-bed rent
~70%Capital back at refi
