A backyard house is one of the best uses of money in Toronto real estate right now. It costs about $300K to build and can rent for about $3,000 a month. The problem is getting there. Add it on top of buying and converting the main house, and you need almost $700K of your own cash.
Most investors don’t have that, so the backyard house stays an idea. But you might not need it. If you break the project into two steps and recycle the money from the main house, you can get the same end result with about $400K. Same cash flow, same cash left in the deal, $300K less out of your pocket. Here’s how it works on a real Toronto deal.
Why a Toronto Multiplex and Backyard House Costs $700K Up Front
Here’s the house. It’s a detached house on a deep lot in a starter Toronto neighbourhood, around $850,000. It’s tired and needs work, but it has a decent backyard to build on. This is the kind of property we see all the time.
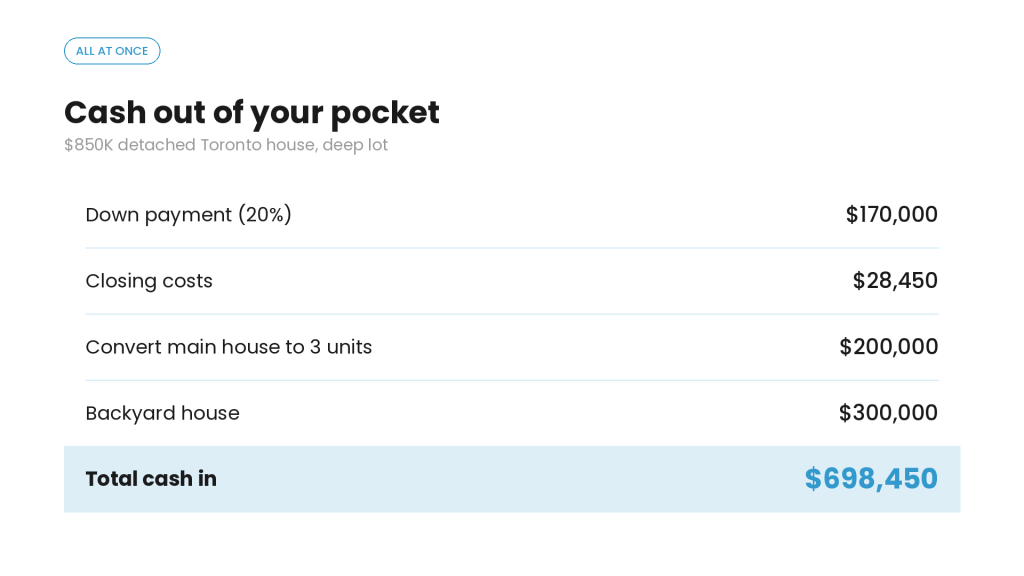
If you do everything at once, here’s the cash you need. The down payment at 20% is $170,000. Closing costs are about $28,000. Converting the main house into three units costs about $200,000. The garden suite in the backyard is about $300,000. That adds up to about $698,000 out of your pocket.
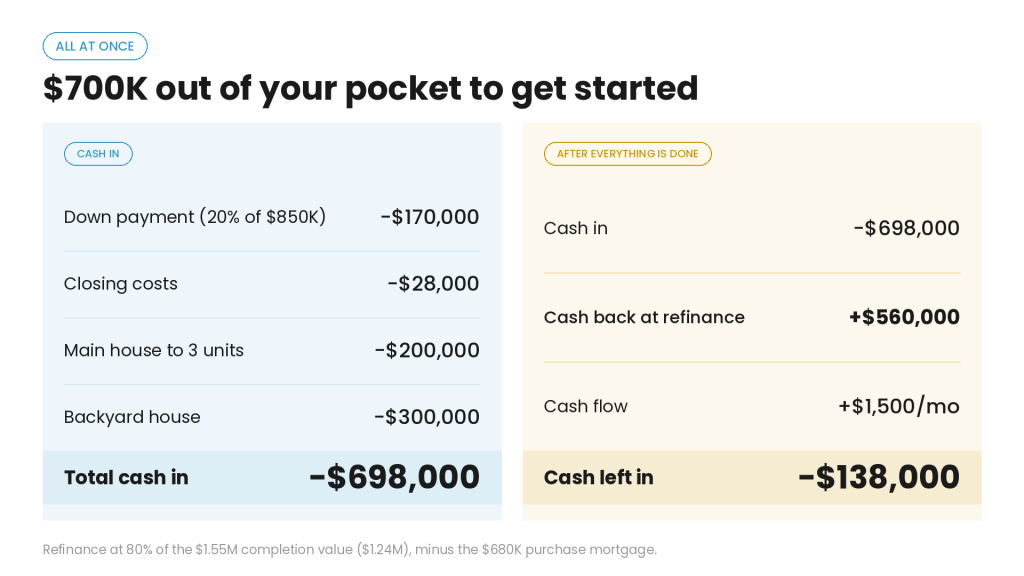
The end result is good. Once everything is done and you refinance, you get about $560K back. You’d have around $140K left in the property, and it would cash flow about $1,500 a month. It’s the $700K to get started that stops most people. In our experience, most of them could afford the main house. It’s the backyard house on top that breaks it.
How a Refinance Gets Your Money Back Out
One idea makes this whole strategy work. When you refinance, the bank doesn’t lend on what you paid. It lends on what the property is worth now. So if you buy a tired Toronto house and turn it into three good units, the value goes up, and the bank will lend you more against it.
Think of it as two values. The initial value is what you paid, $850,000. The bank lends 80% of that, so your first mortgage is $680,000. The completion value is what the property is worth once the work is done. When you refinance at 80% of that new value, the difference between the new loan and your old mortgage comes back to you as cash.
For a Toronto property with four units or fewer, that value comes from condition and from what similar renovated homes nearby have sold for. It doesn’t come from the rent. So the renovation has to be done well, and the comparable sales have to back it up. And here’s what most people miss… if you can pull money out once, you can do it twice.
The Two-Step Plan: Multiplex Conversion First, Backyard House Second
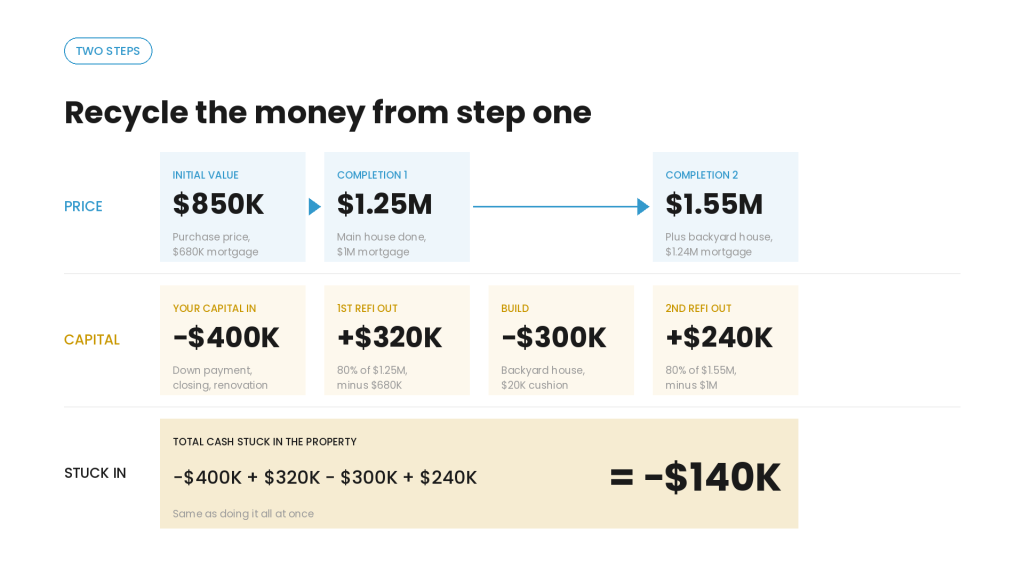
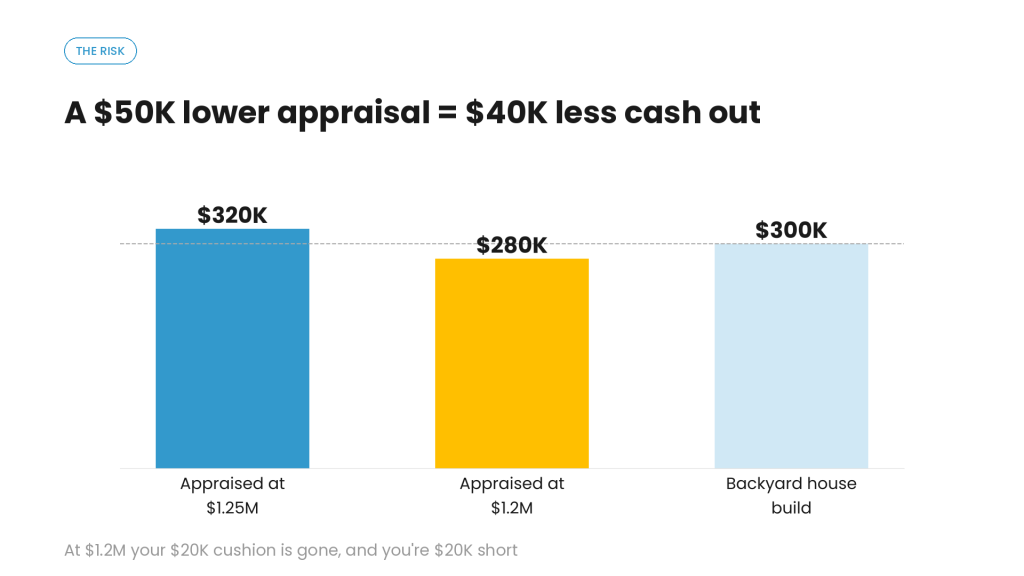
Step one is the main house only. You put in the down payment, closing costs and the $200K renovation, which comes to about $400K. When it’s done and the three units are rented, the house is worth about $1.25 million. The bank lends 80% of that, which is $1 million. Pay off the $680K first mortgage, and about $320K comes back to you.
Step two is the backyard house. The $320K covers the $300K build, with about $20K left over as a cushion. The suite is a three-bedroom renting for about $3,000 a month. On $300,000, that’s about a 12% return a year before expenses, which makes it the biggest cash flow driver in the deal. Once it’s rented, you refinance again. To stay conservative, we value the suite at what it cost. The completion value becomes $1.55 million, the bank lends $1.24 million, and after paying off the $1 million mortgage, you get another $240K back.
Here’s what the cash flow looks like with rents of $2,500, $2,000 and $1,700 in the main house plus $3,000 for the backyard house. That’s $9,200 a month. Before the second refinance, on a $1 million mortgage, it cash flows about $2,733 a month. After it, on $1.24 million, it cash flows about $1,517 a month. That assumes a 4.5% rate, a 30-year amortization and about $1,400 a month for tax, insurance and utilities. The one rule that matters most: don’t start the backyard house until the first refinance is actually done. Not approved in principle. Done.
All at Once vs Two Steps: Same Result, $300K Less Cash
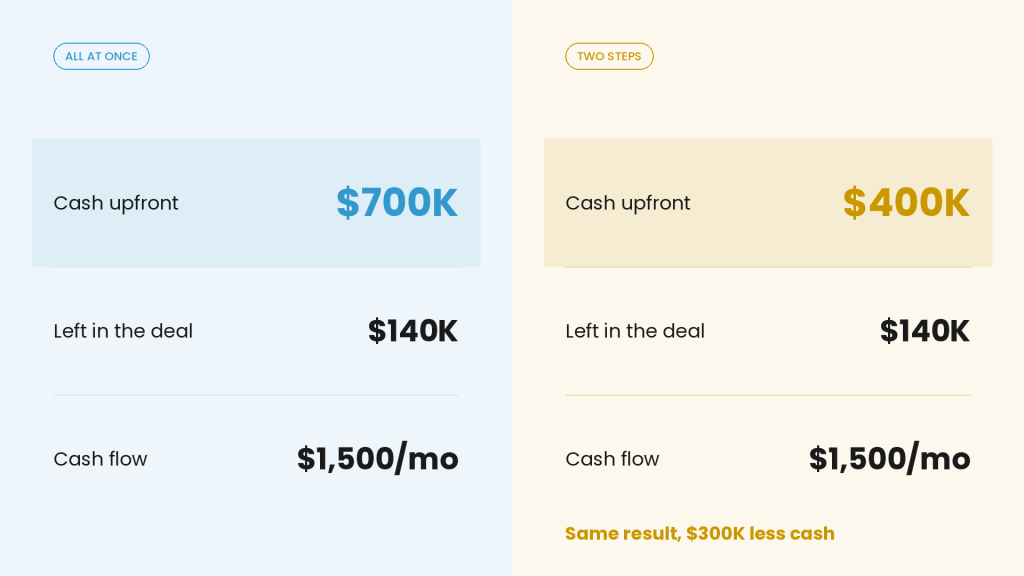
Add up the two-step approach. You put in about $400K, get $320K back, spend $300K on the backyard house, then get $240K back. That leaves about $140K of your money in the property. It’s the same $140K you’d have left in by doing it all at once, with the same $1,500 or so a month in cash flow.
The difference is what you need up front. All at once, you need about $700K of your own cash. In two steps, you need about $400K. There’s another plus, too. With two steps, the main house is already rented while you build the backyard house, so the rent covers the mortgage. Doing it all at once, you carry the whole project with less income coming in.
A question we get a lot: what if you already own a Toronto multiplex with a big backyard? Then you’re basically starting at step two. If your property has gone up in value, or you’ve paid down the mortgage, a refinance might already free up enough to build a garden suite or laneway suite. Same idea, you’re just further along.
The Risks of a Two-Step Refinance, and Who Should Wait
The trade-off is time. Your money is tied up in the project for longer, because there are two rounds instead of one. You’ll pay for two appraisals and two rounds of fees. A longer timeline also means more exposure to the market. Rates can change between steps, and Toronto build costs can creep up. Get a fresh build quote before you refinance, and size your cushion to that number.
The one thing that can break this plan is the appraisal. If the appraiser says $1.2 million instead of $1.25 million, you pull out $40K less. Your $20K cushion is gone, and you’re $20K short for the backyard house. Honestly, $20K is thin on a $300K build, so set more aside if you can. If the appraisal does come in low, you can top up the gap from savings, wait a few months and appraise again, or simply hold a good Toronto triplex for a while. Step one is a solid deal on its own.
To do this, you’ll need about $400K in cash plus a cushion, and you’ll need to qualify for a mortgage of around $680K on the purchase. Some investors should wait. If you need cash flow from day one and don’t want to manage a project, a turnkey Toronto property is simpler. If you have exactly $400K and nothing more, wait until you have a real cushion. And if your income is already stretched by other debts, the refinances might not go through, so sort that out first.
Build Your Toronto Multiplex and Backyard House With a Plan
If a backyard house has felt out of reach because of the cost, it might not be. You don’t need $700K. You need about $400K, the right Toronto property, and a plan for both refinances. The plan is where most of the risk sits: buying a house with real room to add value, budgeting the build properly, and making sure the comparable sales support the completion value.
That’s where working with a team that does this every day matters. We invest in Toronto multiplexes ourselves, and we’ll run the numbers on your actual situation so you know whether the two-step approach works with the cash you have.
Our brokerage specializes in Toronto multiplexes. We’ll help you find deals, crunch the numbers, and guide you through renovations and management. If you want full support in Toronto multiplex investing, our team can help you:- Find high-potential properties
- Crunch the numbers so you know exactly where you stand
- Coach you through renovations to maximize returns
- Lock in great tenants
- Provide full property management so your investment runs smoothly

What Toronto Real Estate Investment Is Right For You?
Check out our complete Toronto real estate investment guide for all the details and real-life examples. If you’re ready to dive in, just book a call with us!
This is for educational purposes only; it does not guarantee future performance or serve as financial or tax advice.
